How the Binomial Model Values Options and Warrants
Learn how the Binomial Model values options and warrants by modeling possible price movements over time, incorporating volatility, exercise price, risk-free rates, and early exercise assumptions.
The Binomial Method is a widely used approach for valuing financial options and warrants. It is particularly useful when the value of the underlying asset may change significantly over time or when the instrument includes features such as early exercise.
Unlike the Black-Scholes model, which generally assumes a continuous pricing framework, the Binomial Method uses a step-by-step tree to model possible changes in the underlying asset price.
What Is the Binomial Method?
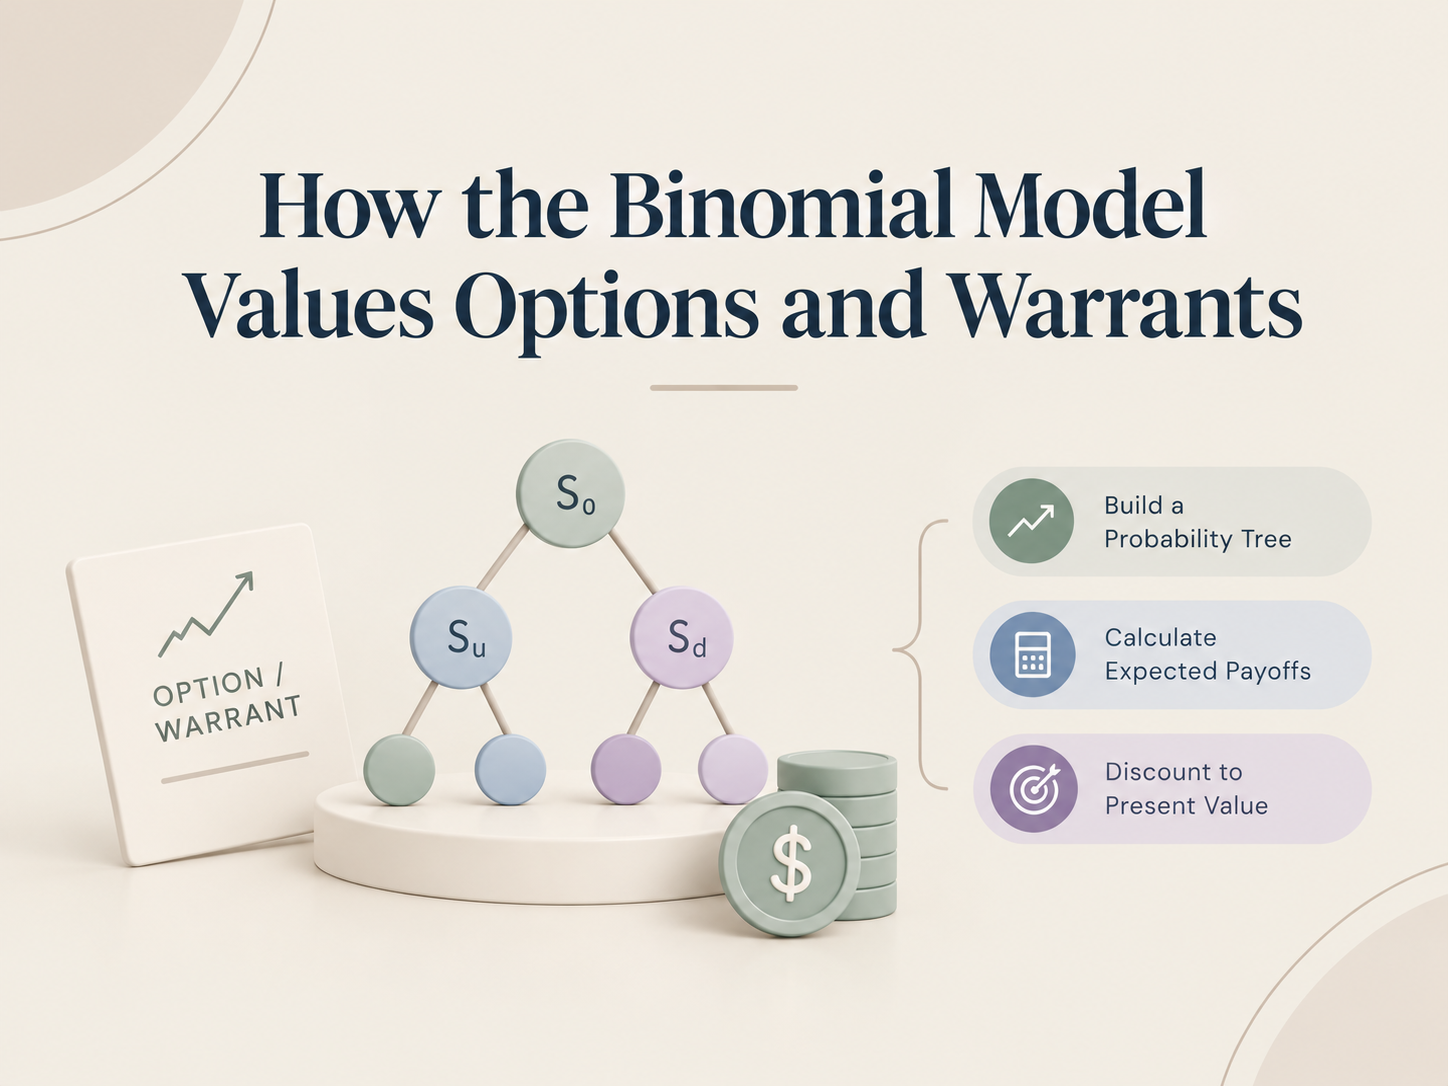
The Binomial Method estimates the value of an option by modelling how the price of the underlying asset can move up or down during different time periods.
At each step, the model calculates the option's value under possible future scenarios. These values are then discounted back to the present using a risk-neutral probability.
The basic structure is:
Current Share Price → Up/Down Price Movements → Option Payoffs → Present Option Value
This makes the method flexible and relatively easy to understand.
How Does the Binomial Model Work?
A typical binomial model involves the following steps:
1. Determine the Key Inputs
The model generally requires:
- Current share price
- Exercise or strike price
- Time to expiry
- Risk-free interest rate
- Expected volatility
- Number of time periods
- Dividend yield, where applicable
2. Calculate Up and Down Factors
The model estimates how much the underlying share price can increase or decrease during each period.
A commonly used formulation is:
u = e^(σ√Δt)
d = 1/u
Where:
- u = up factor
- d = down factor
- σ = volatility
- Δt = length of each time period
The share price can then move upward or downward at each step.
3. Build the Price Tree
Suppose a share currently trades at ₹100. The model may generate future prices such as:
₹100 → ₹110 or ₹92 → further up/down movements
As the number of periods increases, the tree provides a more detailed representation of possible future share prices.
4. Calculate Option Payoffs
At expiry, the option payoff is calculated for each possible share price.
For a call option:
Call Payoff = Max(Share Price − Strike Price, 0)
For a put option:
Put Payoff = Max(Strike Price − Share Price, 0)
5. Work Backwards
The model then moves backwards through the tree, calculating the present value of each possible future payoff.
The risk-neutral probability is commonly calculated as:
p = (e^(rΔt) − d) / (u − d)
Where:
- p = risk-neutral probability of an upward movement
- r = risk-free interest rate
- u = up factor
- d = down factor
The option value at each node is then discounted back to the previous node.
Binomial Method for Warrant Valuation
The Binomial Method can also be used for warrant valuation. A warrant gives its holder the right to purchase shares from the issuing company at a predetermined exercise price.
However, warrants differ from ordinary options because exercising a warrant generally results in the company issuing new shares.
This means warrant valuation may need to consider:
- Existing number of shares
- Number of warrants outstanding
- Exercise price
- Current share price
- Time to expiry
- Volatility
- Risk-free rate
- Expected dilution
Therefore, simply valuing a warrant like a standard option may not always provide an appropriate result when dilution is material.
Simple Example of Binomial Option Valuation
Assume:
- Current share price = ₹100
- Strike price = ₹100
- Time to expiry = 1 year
- Volatility = 20%
- Risk-free rate = 5%
- One-year period divided into two six-month steps
The model first calculates the possible up and down movements in the share price.
At expiry, each possible share price produces a corresponding option payoff. These payoffs are then worked backwards through the tree using risk-neutral probabilities.
The final value at the initial node represents the estimated fair value of the option.
In practice, valuation models generally use many more time steps to produce a more precise estimate.
When Is the Binomial Method Used?
The Binomial Method is commonly considered when valuing:
- Employee stock options
- Warrants
- American-style options
- Convertible instruments with option-like features
- Options with dividends
- Instruments with complex exercise conditions
It can be especially useful when the valuation requires more flexibility than a basic Black-Scholes approach provides.
Conclusion
The Binomial Method in Option and Warrant Valuation provides a flexible framework for estimating the fair value of instruments whose value depends on future movements in an underlying share price. By modelling possible upward and downward price movements and working backwards from the expected payoff, the method can accommodate features such as early exercise, dividends, and other complexities.
For warrant valuation, the model should also consider the impact of newly issued shares and potential dilution. The quality of the valuation ultimately depends on the assumptions used, particularly volatility, time to expiry, interest rates, and the underlying company's capital structure.