Valuation of Convertible Instruments Under US GAAP
Understand how convertible instruments are valued under U.S. GAAP, including key accounting considerations, valuation methods, embedded features, and factors that influence their fair value.
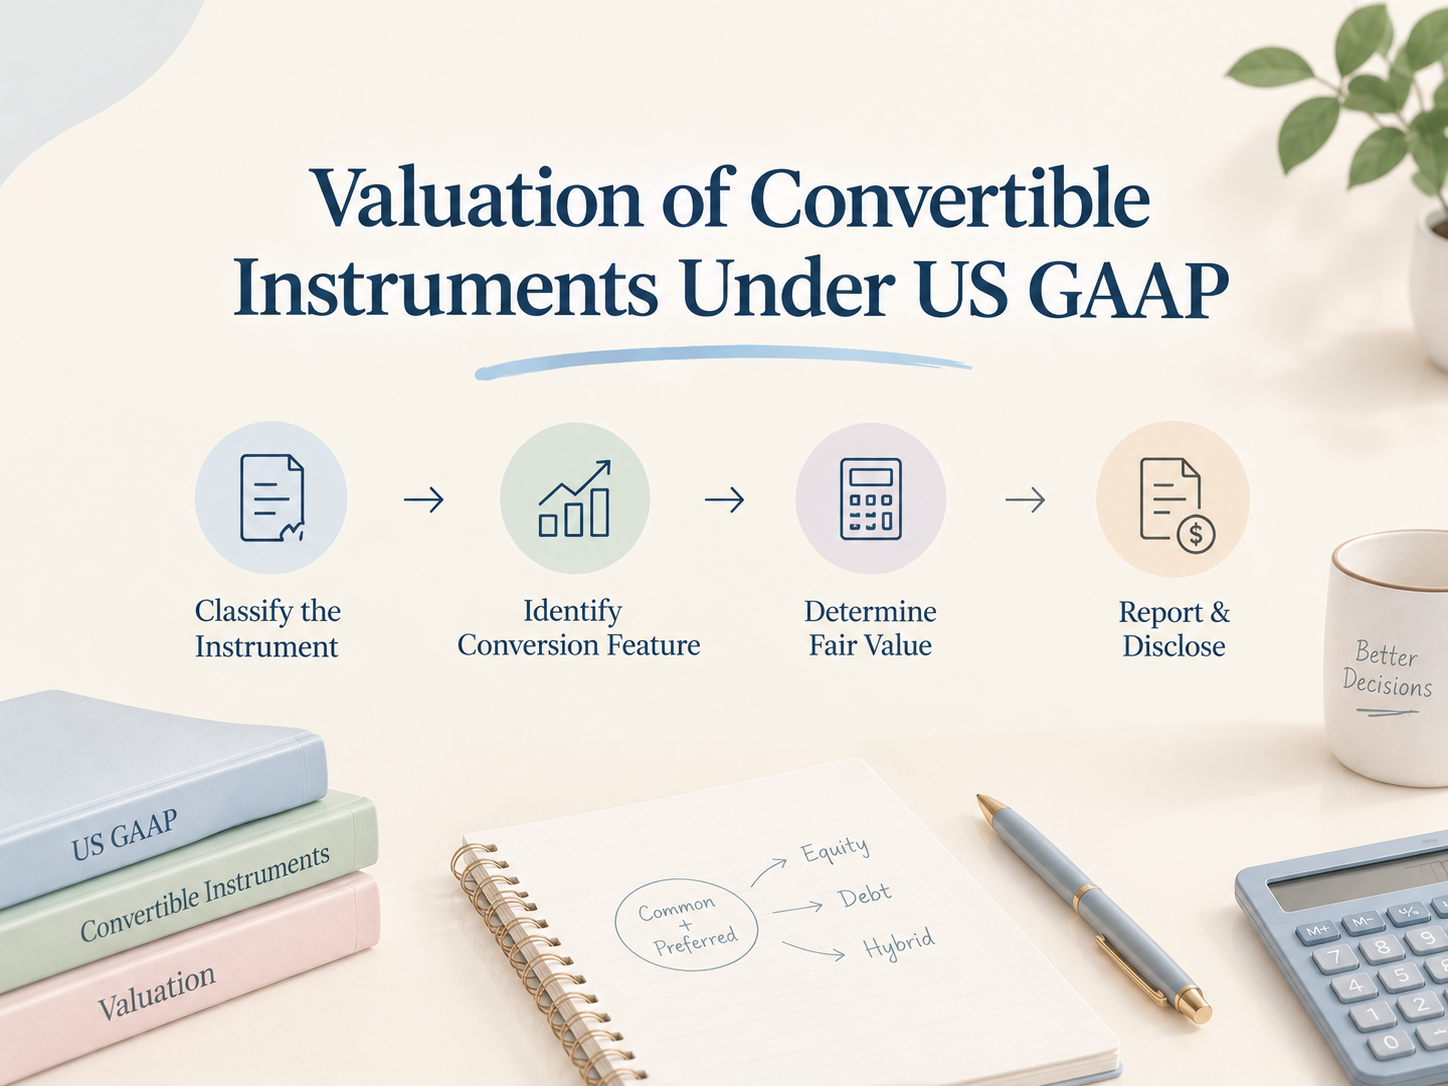
Convertible debt and convertible preferred stock used to trigger one of the most convoluted corners of US GAAP as many as five separate accounting models for convertible debt alone, each requiring its own separation and valuation exercise. ASU 2020-06 changed that substantially, and by 2026, every reporting entity operates under the simplified framework. Understanding what the simplification actually changed, and what it didn't, is essential to valuing these instruments correctly today.
What ASU 2020-06 Actually Removed
The update eliminated the beneficial conversion feature (BCF) and cash conversion feature (CCF) separation models that previously required entities to split a convertible instrument's liability and equity components even when the conversion feature didn't meet derivative criteria. Before this change, a convertible note with an in-the-money conversion feature at issuance, for instance, often required a separate BCF calculation and its own valuation exercise, entirely apart from the host instrument.
Post-adoption, a convertible debt instrument is generally accounted for wholly as a single liability, with no separate equity component recognized, unless one of two conditions applies: the conversion feature requires bifurcation as a derivative under ASC 815, or the instrument was issued at a substantial premium. This is a genuine simplification for a large share of straightforward convertible notes, the valuation exercise has been reduced from multiple separate components to essentially one.
The Two Separation Models That Remain
Derivative bifurcation under ASC 815 still applies where a conversion feature is not clearly and closely related to the host contract, meets the definition of a derivative, and doesn't qualify for a scope exception. A standard conversion feature that converts a fixed amount of debt into a fixed number of shares will typically pass the relevant tests and avoid bifurcation entirely. It's specifically the non-standard features that trigger this treatment.
Substantial premium accounting applies in the comparatively rare situation where a convertible instrument is issued at a price meaningfully above its face value, requiring the premium itself to be allocated separately, generally to additional paid-in capital.
Where bifurcation is required, the embedded conversion feature must be valued separately at fair value, typically using a binomial model or Monte Carlo simulation given the option-like payoff structure, with subsequent remeasurement at each reporting date running through earnings precisely the same valuation discipline required for SPAC warrants and other ASC 815-40 instruments.
Why Getting the Bifurcation Analysis Right Matters So Much
The real question is whether this conversion feature needs to be split into two parts or if it can be handled under the single-liability method. That’s where the actual valuation and accounting judgment comes into play. Getting this analysis wrong doesn't just misstate one number; it determines whether an entire separate fair value measurement, remeasured every reporting period, is required at all. A misclassified instrument can understate genuine earnings volatility for years if a bifurcation requirement is missed, or create unnecessary quarterly remeasurement burden if bifurcation is incorrectly applied where it wasn't actually required.
Convertible Preferred Stock Follows a Parallel but Distinct Path
ASU 2020-06 reduced the available accounting models for convertible preferred stock from four to three, following broadly the same logic as convertible debt — fewer embedded features get separately recognized from the host instrument. The practical valuation implication is similar: absent a derivative-qualifying conversion feature, convertible preferred stock is generally valued and accounted for as a single instrument rather than split into separately measured components.
The EPS Calculation Change Matters for Valuation Context
Beyond balance sheet treatment, ASU 2020-06 eliminated the treasury stock method for calculating diluted earnings per share involving convertible instruments, requiring the if-converted method universally instead. While this is an EPS mechanic rather than a valuation method itself, it directly affects how a company's diluted share count, and therefore its per-share metrics, get presented relevant context for anyone using comparable company multiples that reference diluted EPS.
For most straightforward convertible debt and preferred stock issued today, ASU 2020-06 has genuinely simplified the valuation exercise down to a single instrument, valued as a whole. The real technical work now focuses entirely on the bifurcation threshold question: does a specific conversion features terms trigger ASC 815 derivative treatment because that single determination decides whether a separate recurring fair value exercise is required at all.