409A Valuation Trends by Sector: 2026 Insights
Explore 2026 409A valuation trends across key sectors, including how industry growth, revenue multiples, risk, market conditions, and sector-specific factors influence private company valuations.
A 409A valuation is only as good as the assumptions behind it. In 2026, those assumptions can look very different depending on the industry a company operates in.
Revenue multiples, discount for lack of marketability (DLOM), and the relationship between common and preferred stock can vary significantly between sectors. A benchmark that makes sense for a fast-growing SaaS company may have little relevance for an early-stage biotech business. Using the wrong industry benchmark can therefore lead to a valuation that does not properly reflect the company’s actual risk and growth profile.
Why Does Industry Matter So Much?
Industry has a direct influence on many of the assumptions used in a 409A valuation.
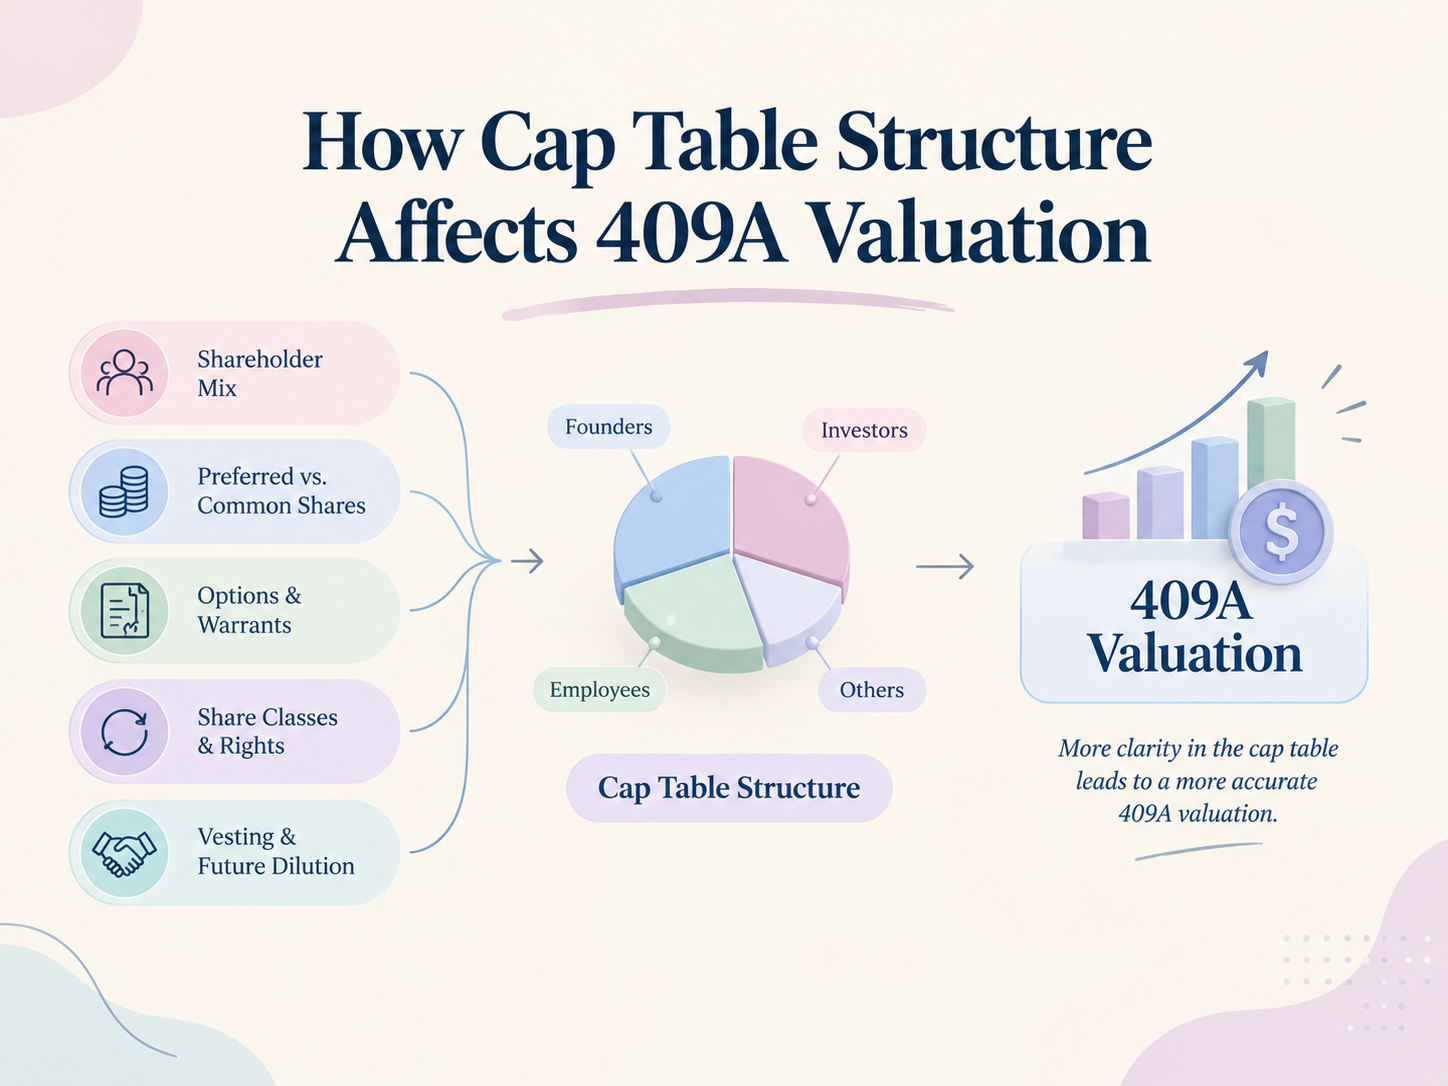
The common-to-preferred stock ratio, for example, is influenced by factors such as the expected timing of a liquidity event and the uncertainty surrounding the company’s path to that event. Companies operating in markets with relatively predictable revenue and plenty of comparable transactions generally provide more data for valuation models.
That is very different from sectors where companies may spend years developing a product before generating meaningful revenue. In those cases, the valuation depends much more heavily on future milestones and projected outcomes. The greater uncertainty can result in a wider difference between preferred and common stock values and can also affect the DLOM applied in the analysis.
Where Do Different Sectors Stand in 2026?
SaaS and B2B Software
SaaS and B2B software companies continue to show relatively high common-to-preferred ratios at the seed stage, with benchmarks in some analyses falling around 12% to 28%.One reason is the depth of available market data. SaaS has a large pool of public-company comparables, private transactions, and established revenue-based valuation metrics. At later stages, growth rates can have a significant effect on revenue multiples. High-growth SaaS companies growing more than 40% annually may command forward revenue multiples of roughly 8x to 14x, while companies with moderate growth may fall closer to 5x to 9x. More mature SaaS businesses with growth below 20% may see multiples closer to 3x to 6%.
The exact multiple, however, depends on more than growth alone. Margins, retention, customer concentration, scale, and the quality of recurring revenue can all influence the analysis.
Biotech and Life Sciences
Biotech presents a very different valuation challenge.Early-stage biotech companies can have common-to-preferred ratios in the range of roughly 5% to 15%. Long development timelines and significant clinical and regulatory uncertainty can make the value of common stock substantially more sensitive to the timing and probability of future milestones.Traditional revenue multiples often have limited usefulness at this stage because the company may have little or no meaningful revenue.
Instead, valuation models may place greater weight on scenario-based analysis, including potential clinical outcomes, regulatory milestones, commercialization assumptions, and the probability of reaching each stage.
Fintech
Fintech generally falls somewhere between traditional software and more development-intensive sectors.Seed-stage companies may show common-to-preferred ratios in the range of approximately 10% to 22%. Regulatory considerations can also introduce additional uncertainty, depending on the company's business model and the markets in which it operates.
At later stages, revenue multiples may be more modest than those seen in high-growth SaaS. Multiples in the range of 2x to 5x can be relevant in some situations, although fintech businesses are often evaluated using a combination of revenue, gross profit, transaction volume, and other sector-specific metrics.
AI and Deep Tech
AI and deep tech have become particularly interesting from a valuation perspective. Some vertical AI companies are attracting forward revenue multiples in the 10x to 25x range, but the spread between companies can be substantial. Investors and valuation professionals are still assessing how durable competitive advantages will be, how quickly products can be replicated, and whether current growth rates can be sustained.
That uncertainty can carry directly into a 409A valuation. Rather than relying on a broad AI benchmark, it becomes particularly important to explain why specific comparable companies and transactions were selected and how the assumptions relate to the company being valued.
Hardware and Capital-Intensive Businesses
Hardware businesses generally face a different set of valuation considerations.Seed-stage hardware companies may have common-to-preferred ratios around 6% to 18%, with capital requirements and longer paths to commercial-scale revenue contributing to the relatively conservative benchmarks.
Manufacturing requirements, inventory needs, working capital, supply-chain risks, and the need for additional financing can all affect the valuation.
What Is Changing in 2026?
Industry benchmarks are also being affected by broader changes in the private market. For example, bolt-on and add-on transactions accounted for 58.6% of private equity deal volume in Q1 2026, while traditional platform-formation buyouts accounted for 18.2%. Activity has been particularly visible in areas such as healthcare, home services, professional services, and industrials.
For valuation professionals, this highlights the importance of using recent and genuinely comparable transactions rather than relying too heavily on older market data.Another change is the growing availability of technology-assisted 409A valuation platforms. Some providers now offer relatively low-cost, standardized valuations for straightforward early-stage companies, with prices at the lower end reported around $499.
That can be useful for simpler situations, but companies with complex capitalization tables, multiple preference layers, unusual securities, or cross-border ownership may still require significantly more detailed modelling and professional judgment.
Industry should not be treated as a minor input in a 409A valuation. It can influence the selection of comparable companies, revenue multiples, expected exit timing, DLOM, common-to-preferred relationships, and even the valuation methodology itself.
A SaaS company and a biotech company may have similar headline valuations, but the assumptions supporting those valuations can be completely different. Applying SaaS-style revenue multiples to a pre-revenue biotech company, for example, may create a level of precision that the underlying business simply does not support.
The better approach is to start with the company itself i.e. its industry, stage, growth profile, capital structure, risks, and expected path to liquidity and then select benchmarks that genuinely reflect those characteristics.
In a 409A valuation, the most useful benchmark is not necessarily the industry average. It is the benchmark that can be clearly supported as relevant to the company being valued.