Loading…


Loading…
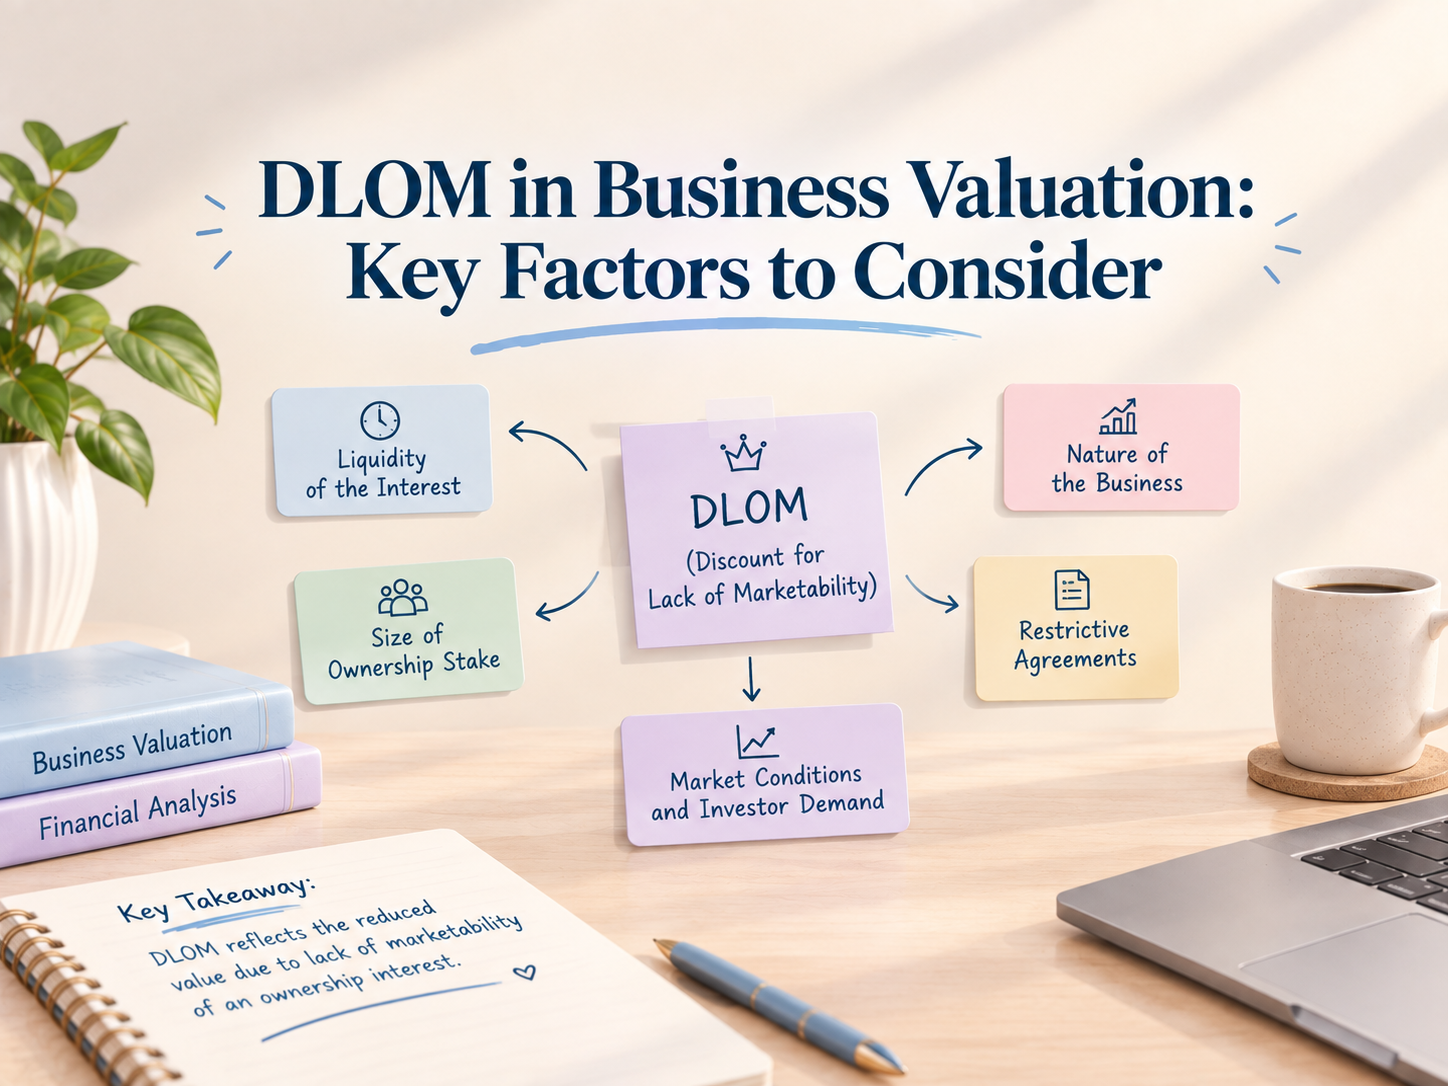
Understand the Discount for Lack of Marketability (DLOM), including the key factors valuation professionals consider, common methodologies, and how marketability affects the value of privately held business interests.
A share in a listed company can be sold within seconds at a price to everyone. A share in a company cannot. There is no ready buyer there is no public price and often there is no clear exit, for months or years. The Discount for Lack of Marketability (DLOM) exists to price exactly this difference, and it's one of the most consequential, and most frequently misapplied, adjustments in private company valuation.
What DLOM Actually Addresses
DLOM is distinct from the Discount for Lack of Control, even though the two are often applied together and sometimes confused. DLOC prices the absence of power to direct a company's decisions. DLOM prices the absence of a ready market to convert the holding into cash. A person who owns a lot of shares in a company still has a problem when it comes to selling all of it. There might not be someone ready to buy the whole company today. Even though that person doesn't have any issues, with controlling the company at all. The two discounts address genuinely separate risks, and applying one doesn't substitute for properly assessing the other.
The Standard Methods Used to Estimate DLOM
Restricted stock studies look at the price of shares that anyone can buy and sell on the market compared to the price of shares that are not allowed to be sold for a time period. These two types of shares are the same in every way except, for the fact that one group can't be sold for a set amount of time. The gap between the two prices is attributed directly to illiquidity, and historically these studies have shown discounts in a fairly wide range, commonly cited as roughly 20% to 35%, though this varies considerably by holding period and market conditions.
Pre-IPO studies compare private transaction prices in a company's own shares against the price the same shares eventually fetched once the company actually went public. This tends to produce higher indicated discounts than restricted stock studies, since a pre-IPO holding faces a considerably longer, less certain path to liquidity than a lock-up with a known expiry date.
Option pricing models, like the Chaffe or Finnerty models look at the fact that you can't sell an asset for a time and see it as if you're missing a put option. That means you don't have the protection of being able to sell at a price if things go wrong. The cost of not having that protection is how these models estimate the marketability discount. These models are attractive because they're grounded in observable volatility rather than historical study averages, though the resulting discount is highly sensitive to the volatility assumption fed into it.
The Factors That Actually Move the Number
A defensible DLOM isn't pulled from the midpoint of a study's reported range. It's built from specific, company-level factors:
Prospect of a near-term liquidity event. A company with a credible path to an IPO or acquisition within twelve to eighteen months warrants a meaningfully lower DLOM than one with no visible exit on the horizon at all.
Dividend policy. A private company that pays regular dividends offers shareholders some return while they wait for an exit, which tends to reduce the appropriate discount relative to a company retaining all earnings indefinitely.
Size and financial health of the company. Larger, more established, profitable businesses generally warrant a lower DLOM than smaller, less stable ones, since a larger business is inherently a more plausible acquisition or listing candidate.
Restrictive transfer provisions. Shareholders' agreements that impose rights of first refusal, drag-along obligations, or outright transfer restrictions can push the appropriate discount meaningfully higher, since they constrain the pool of potential buyers even if a willing one were found.
Why a Flat, Rule-of-Thumb Discount Doesn't Hold Up
Applying a standard 20-25% DLOM without examining these company-specific factors is one of the most common weaknesses found in valuation reports facing genuine scrutiny whether from a tax authority reviewing a Rule 57 valuation, an auditor examining an Ind AS 102 ESOP valuation, or an opposing expert in a shareholder dispute. Two private companies of similar size and sector can warrant very different DLOMs if one has a credible IPO timeline and the other has no visible exit path whatsoever.
DLOM should be treated as a company-specific analysis, not a benchmark pulled from an industry survey and applied uniformly. A defensible figure considers the company's actual liquidity prospects, its dividend history, its size, and any contractual transfer restrictions — triangulated across more than one estimation method rather than resting on a single study's average. Getting this number right often matters as much to the final valuation as the discount rate or growth assumptions that came before it.


