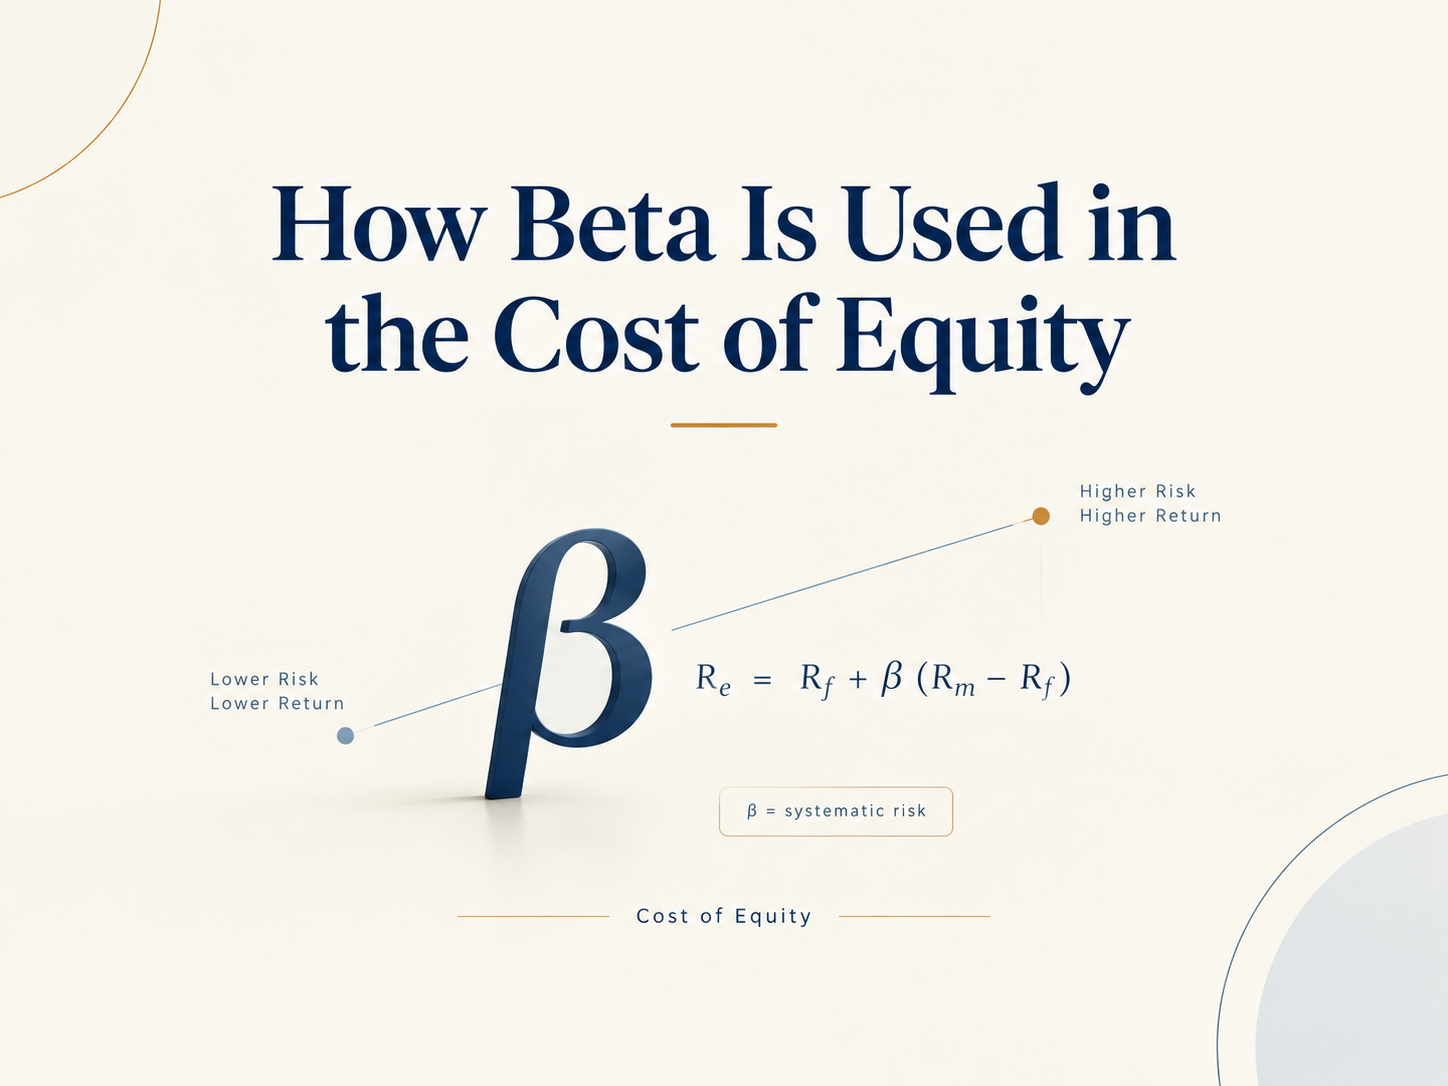
How Beta Is Used in the Cost of Equity
Understand how beta measures a company’s systematic risk and how it influences the cost of equity, required returns, discount rates, and ultimately business valuation.
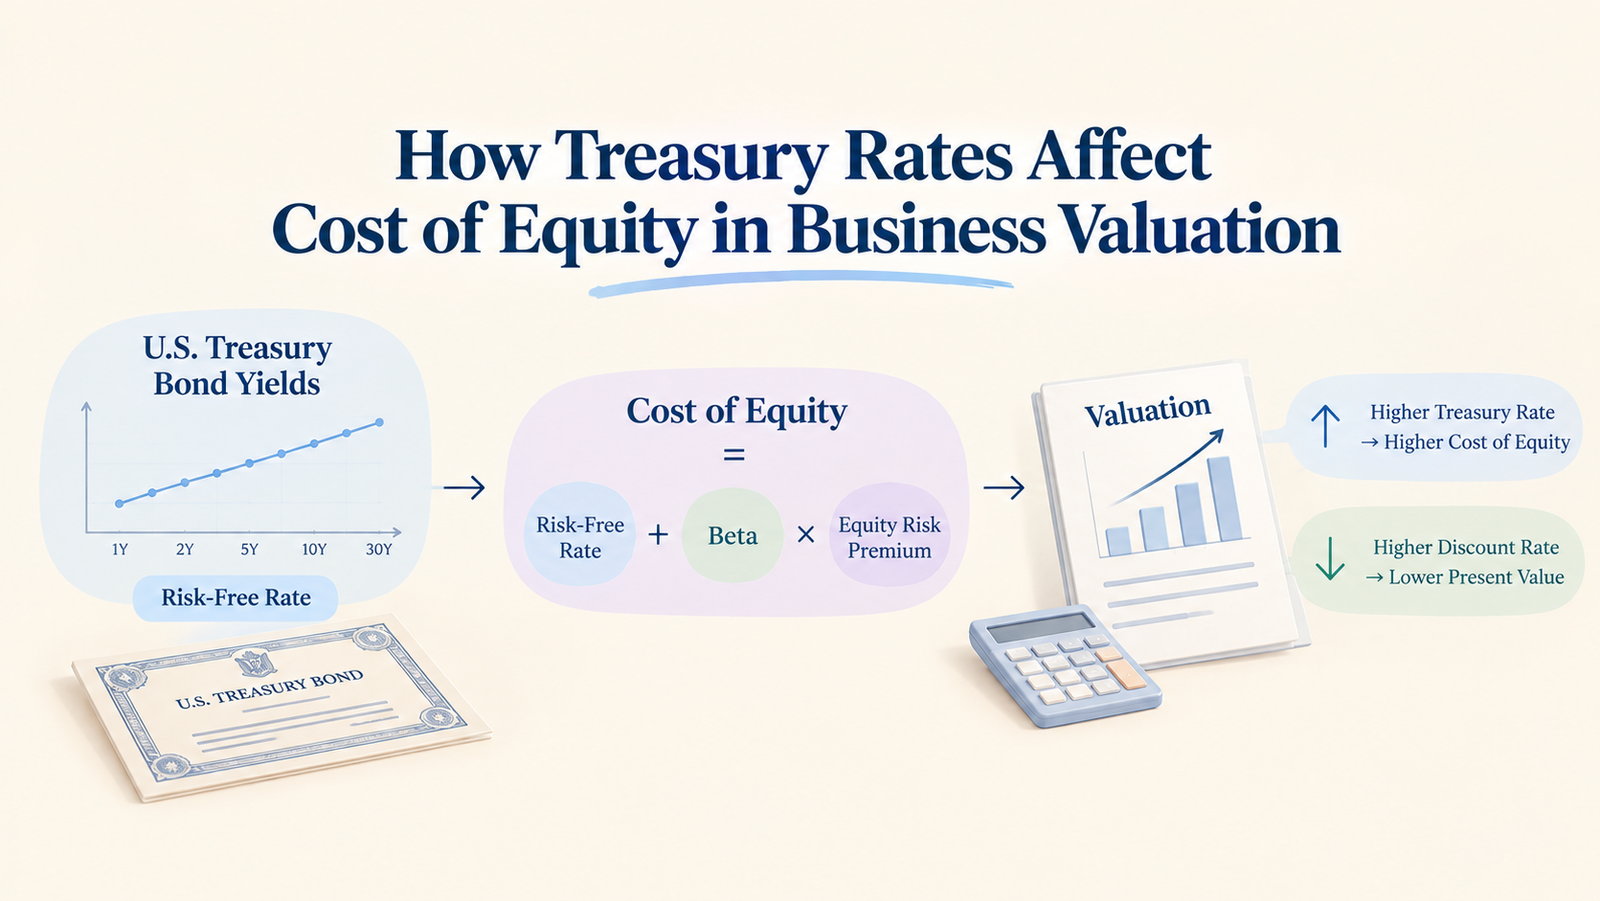
Beta is one of the most misunderstood inputs in the Capital Asset Pricing Model (CAPM). It often looks like a simple number pulled from a financial database, but using the right beta particularly for a private company involves considerably more judgment than simply looking up a figure.
What Does Beta Actually Measure?
Beta measures how sensitive a stock's returns have historically been to movements in the broader market. In other words, it captures systematic risk — the portion of investment risk that cannot be eliminated simply by holding a well-diversified portfolio. A beta of 1.0 indicates that a stock has historically moved broadly in line with the market. A beta above 1.0 suggests that the stock tends to experience larger movements than the market, while a beta below 1.0 indicates relatively smaller movements.
It is important not to confuse beta with total business risk. A company can have significant operational risks such as dependence on a single customer or high levels of debt without necessarily having a high beta. If those risks are not closely related to overall market movements, they may not show up strongly in beta.
This distinction is important because CAPM is designed to compensate investors for systematic risk, not company-specific risk that can theoretically be diversified away.
Levered vs. Unlevered Beta
A observed or levered beta of a company reflects both the underlying business risk and the additional financial risk associated with its capital structure. Unlevered beta, sometimes called asset beta, removes the effect of financial leverage and focuses more directly on the underlying risk of the business itself.
This distinction becomes important when comparing companies. Two businesses operating in the same industry may face broadly similar operating risks but have very different betas because one uses significantly more debt than the other.
Unlevering the beta helps make the comparison more meaningful. A commonly used approach is the Hamada equation, which adjusts for the company's debt-to-equity ratio and applicable tax rate.
Why Private Company Valuation Requires This Adjustment
A private company does not have a publicly traded stock, so there is no directly observable beta to use in a CAPM calculation. Instead, the beta generally needs to be estimated using comparable publicly traded companies.
A typical bottom-up process involves:
- Selecting a relevant group of comparable public companies.
- Unlevering each company's observed beta.
- Using the resulting unlevered betas to develop an appropriate estimate of business risk.
- Relevering the selected beta using the private company's actual or expected capital structure.
Simply taking the levered beta of one public company and applying it directly to a private company can produce a misleading cost of equity, particularly when the two companies have significantly different levels of financial leverage.
Raw Beta vs. Adjusted Beta
Historical, or raw beta is generally estimated through a regression of a stock's historical returns against the returns of a market index over a specified period.
The result can vary depending on the lookback period, return interval, and market index used. A two-year monthly regression, for example, may produce a different beta from a five-year weekly regression. Some data providers report an adjusted beta rather than the raw regression result. Adjusted beta typically moves the historical beta partway toward 1.0 based on the observation that betas tend to move toward the market average over time.
This is worth checking when using third-party data. If the sourced beta has already been adjusted, it should not be treated as though it were a raw regression beta.
Why the Bottom-Up Approach Is Often More Defensible
Rather than relying on a single comparable company's beta or using a broad industry beta without further analysis, a bottom-up beta is generally more robust. The process involves selecting a genuinely comparable peer group, unlevering the individual betas, considering the resulting range or central tendency, and then relevering the selected beta for the subject company's capital structure.
Using several comparable companies helps reduce the influence of company-specific noise in any one stock's historical beta. It also provides a more transparent basis for explaining why the selected beta is appropriate for the company being valued. The quality of the result, however, still depends heavily on the quality of the peer group.
Key Limitations to Consider
Beta can change depending on the measurement period. Different lookback periods and return frequencies can produce materially different estimates, even when there has been no fundamental change in the underlying business.
Thinly traded stocks can produce unreliable estimates. Where trading activity is limited, the statistical relationship between the company's returns and market returns may contain considerable noise.
A poor peer group can undermine the entire analysis. Companies may operate in the same broad industry but have very different business models, geographic exposure, customer bases, growth profiles, or financial structures. Simply being classified within the same sector does not make a company an appropriate comparable.
Beta may appear to be a single, objective number, but a defensible cost of equity calculation requires judgment at several stages. The analyst needs to select appropriate comparable companies, understand whether the sourced betas are raw or adjusted, remove the impact of differences in capital structure, and then apply an appropriate leverage assumption to the subject company.
For private company valuations in particular, beta should therefore be treated as a derived valuation input rather than a number that can simply be looked up. The methodology used to arrive at it can be just as important as the final figure itself.