How USD Exchange Rates Affect Company Valuation
Explore how USD exchange rate movements can affect company valuation through foreign revenues, costs, cash flows, earnings translation, currency risk, and discount rate assumptions.
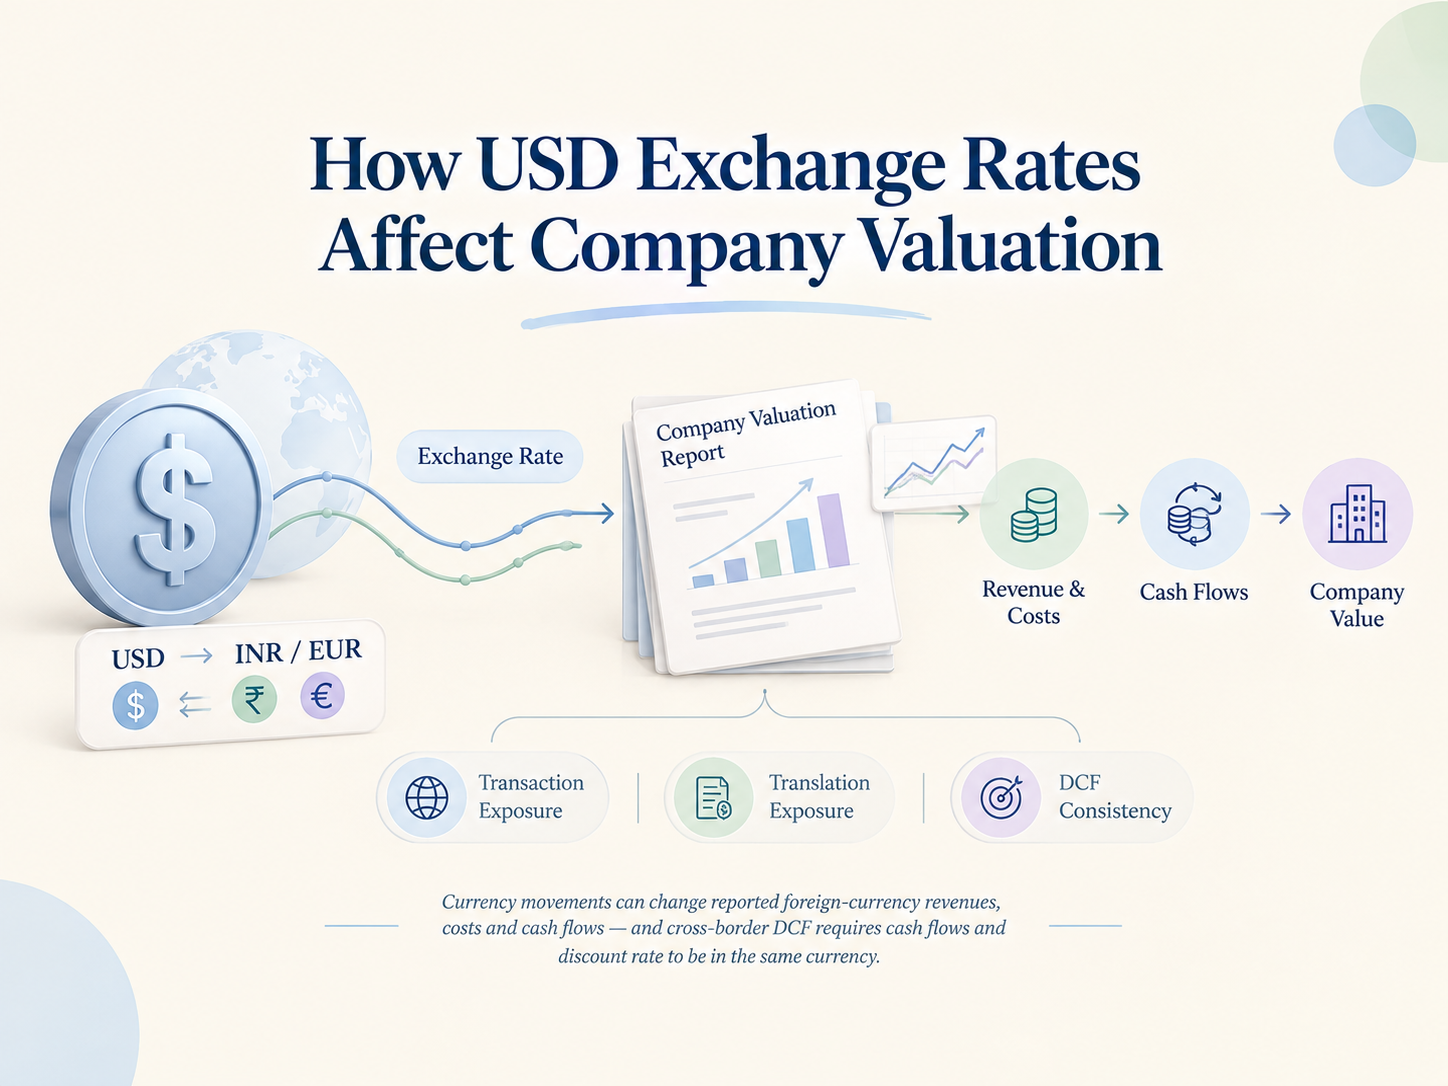
For any company that is not based in the United States and that has revenue, costs or debt in U.S. Dollars changes, in the U.S. Dollar exchange rate are not a small part of the valuation. They affect cash flow projections, discount rates and comparable company analysis.
Three Distinct Types of Currency Risk
Transaction risk comes from cash flows that are set in a currency. This can happen when a company sells goods abroad and gets paid in dollars or buys something from another country and pays in dollars. It also includes paying back a loan that is written in dollars. These situations create risk because exchange rates can change before the money is actually exchanged.This risk is concrete and often partially hedgeable through forwards or options, and a valuation should reflect whether such hedges are actually in place, since a hedged and unhedged company with identical dollar exposure carry genuinely different risk profiles.
Translation risk arises when financial statements prepared in one currency get translated into another for reporting , a foreign subsidiary's results translated into a US parent's dollar financials, or the reverse. This affects reported figures without necessarily affecting the business's actual economic reality, so a valuer needs to look past translated financials to the currency the business genuinely operates in.
Economic risk is the broadest and hardest to quantify: the effect of exchange rates on competitive position and long-term cash flows, independent of any hedged transaction or accounting translation. A dollar appreciation making a company's exports less competitive against rivals pricing in their own currency represents economic risk and this can't be hedged away with a forward contract.
How This Flows Into a DCF Valuation
The cleanest approach treats a business in its currency – the main economic environment the business actually operates in – with a discount rate and growth assumptions that match that currency’s own inflation and risk. At the final step does the cleanest approach convert, to a different reporting currency.
A common, consequential mistake is mixing currencies partway through a model, projecting cash flows in local currency but applying a discount rate built from a different currency's risk-free rate, without adjusting for the inflation differential between the two. This inconsistency introduces a distortion that has nothing to do with the underlying business and everything to do with a modeling error.
Comparable Company Analysis Across Currencies
Applying a multiple derived from dollar-denominated public comparables to a company with substantially different currency exposure requires real caution. The multiples of a US comparable set contain conditions that're specific to the dollar. These dollar conditions include US interest rates, the risk appetite of US investors and expectations, for USD growth. Those dollar conditions may not transfer cleanly to a company whose cash flows and competitive dynamics sit in a currency that's not the dollar.
This is particularly relevant for exporters and multinationals, where a portion of revenue is dollar-linked while costs remain in local currency, creating a mismatch within the business itself that a single blended multiple can easily obscure.
Implications for Cross-Border Valuations and Deals
USD strength or weakness directly affects the relative purchasing power in cross-border acquisitions, and by extension, the practical economics of a deal even when the target's own standalone valuation hasn't changed.When a dollar‑denominated acquirer looks at a target that is priced in a local currency the acquirer gets more purchasing power during a period of dollar strength. This extra purchasing power changes the deal timing. Gives the acquirer more negotiating leverage even when the target’s fundamental value is unchanged.
Practical Implications for a Valuation Prepared Today
Identify the company's actual currency exposure explicitly. Transaction, translation and economic. Rather, than treating currency risk as a single undifferentiated factor folded into a generic risk premium.
Keep the valuation currency internally consistent, matching cash flow projections, discount rate components, and growth assumptions to the same currency throughout the model, converting only at the final step if a different reporting currency is required.
Match comparable companies by genuine currency exposure, not simply by listing location, since two companies both "listed in dollars" can have very different underlying currency risk profiles.
USD exchange rate movements impact valuation, in three ways. Through contracted transactions, accounting translation and economic competitiveness. Each of these affects the valuation differently so they need to be treated in any model. Collapsing all of this into a single, vague currency adjustment is one of the more common and avoidable sources of a distorted cross-border valuation.