Loading…


Loading…
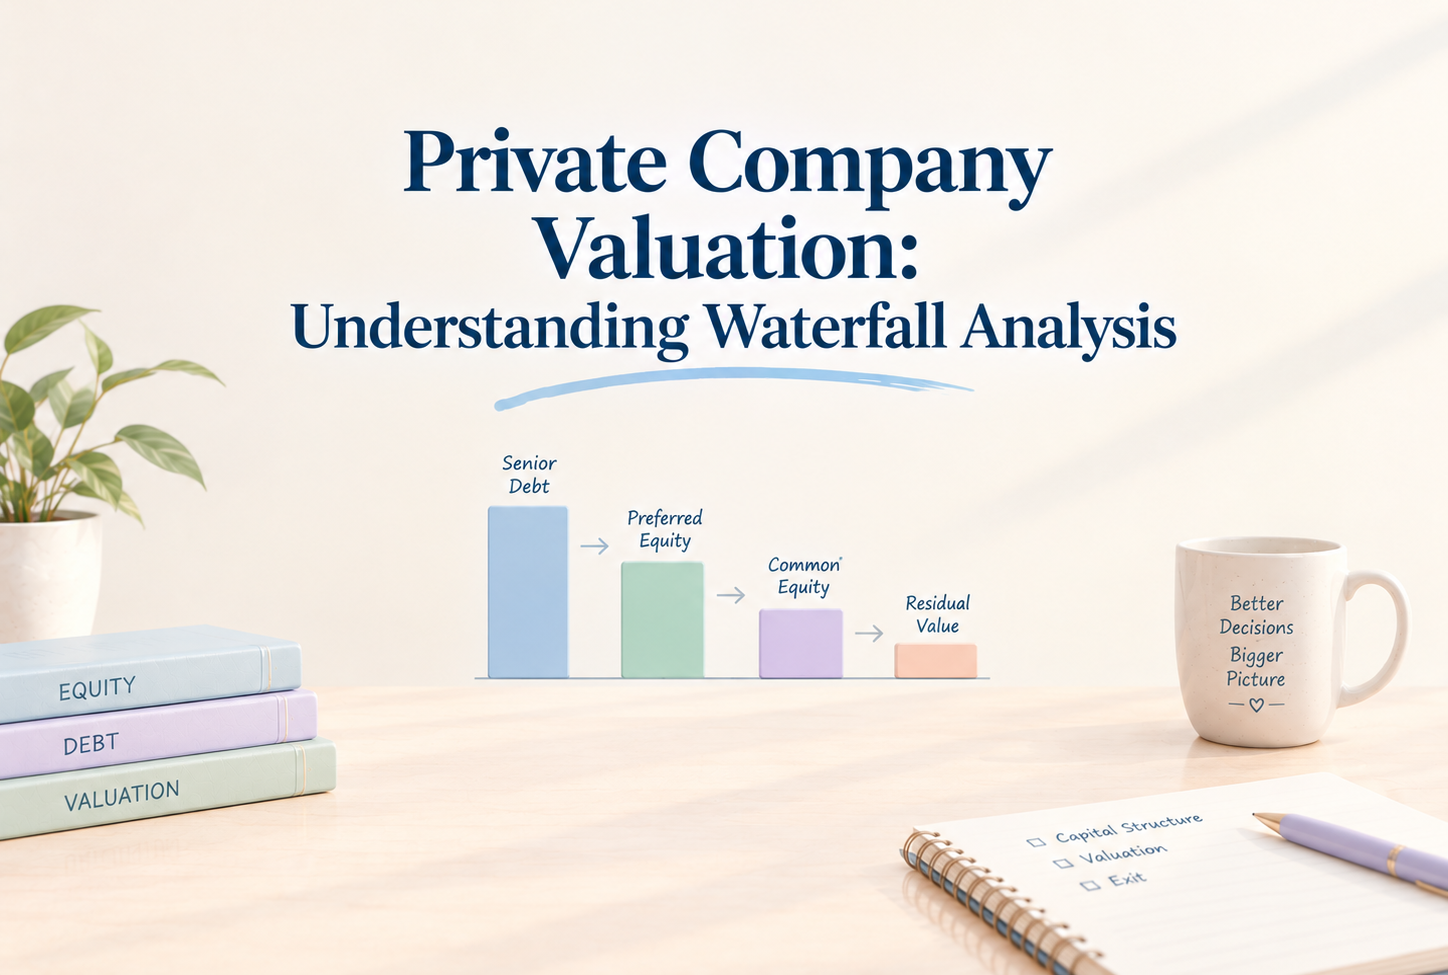
Learn how waterfall analysis works in private company valuation, including how equity value is allocated across different share classes, preferences, and ownership interests.
Two investors can put money into the exact same private company, at the exact same time, and still walk away with very different payouts when the company is eventually sold. That's not a mistake, it's the entire point of a waterfall analysis. Understanding how proceeds actually flow through a private company's capital structure is one of the most important, and most overlooked, parts of valuing that company correctly.
What a Waterfall Analysis Actually Does?
A waterfall analysis models exactly how the proceeds from a sale, liquidation, or other exit event get distributed among a company's different classes of investors and shareholders. The name comes from the idea of proceeds flowing down through a series of tiers. Each tier is a class of security. Each tier of security gets paid according to its rights and priority. Whatever is left from the tier of security trickles down to the tier of security, in line.
This is really important for companies because not every share is the same. A company that has gone through rounds of funding usually has different types of preferred stock. Each type has its rules, about how it gets paid first how it can turn into common stock and where it stands compared to other shares. All of these are added on top of the stock that founders and employees own.Simply dividing total proceeds by ownership percentage, the way you might with a single class of stock, would produce a badly wrong answer.
Why Liquidation Preference Changes Everything
The starting point of any waterfall is liquidation preference. It is the right of preferred shareholders to receive a specified amount before common shareholders receive anything at all. This is typically expressed as a multiple of the original investment, most commonly 1x, meaning an investor is entitled to get their original money back before anyone else sees a dollar.
Here's where it gets more complex: preference can be participating or non-participating. With a -participating preference an investor gets to pick the better of two options. They can take the liquidation preference or they can convert to common stock and get their pro-rata share instead. It's all, about choosing what gives them value in the end. With participating preference, an investor gets their liquidation preference back first, and then still participates alongside common shareholders in whatever remains. This double-dipping feature can meaningfully shift outcomes in the investor's favor, particularly in a modest exit where there isn't much value to go around.
Seniority: Who Gets Paid First
Beyond the size of each class's preference, a waterfall also depends on ranking i.e. the order in which different classes get paid. In a company with multiple funding rounds, later investors are usually granted senior liquidation preference over earlier investors, meaning a Series C investor typically gets paid out before a Series A investor, who in turn gets paid before common shareholders.
Some deals use "pari passu" structures instead, where multiple classes share proceeds proportionally rather than strictly in sequence. Getting this ranking wrong or missing a side letter that gives an investor senior rights. It is one of the most common and serious mistakes when building a waterfall model. This ranking error can cause problems, for a waterfall model.
Working Through an Exit Scenario
To see why this matters, imagine a company that has raised a Series A round with a 1x non-participating preference and a Series B round with a 1x participating preference, on top of common equity held by founders and employees. If the company sells for an amount. Big enough that turning into common stock gives more, than just taking the preference. The Series A investor will usually convert. The Series B investor, thanks to participating preference, takes their preference back first and then still shares in the remaining proceeds alongside everyone else.
Now imagine the same company sells for a much smaller amount instead. In that scenario, the Series A investor is far better off simply taking their liquidation preference rather than converting, since their pro-rata share of a small pie would be worth less. The waterfall in this lower-value scenario looks completely different from the one in the high-value scenario, even though the ownership percentages never changed. This is exactly why a single exit price assumption isn't enough — a proper waterfall needs to be modeled across a realistic range of outcomes.
Why Waterfall Analysis Is Central to CCPS and Option Pricing
Waterfall modeling isn't just relevant at the moment of an actual exit. It's a foundational input to valuing convertible instruments like CCPS, and to option pricing methods used for 409A-style valuations and other fair value exercises. The Option Pricing Method, in particular, relies directly on the waterfall to determine the "strike price" at which each class of security starts participating in value, since each class effectively behaves like a call option struck at the point where its preference is fully satisfied.
Getting the waterfall wrong doesn't just misprice a hypothetical exit, it distorts the fair value calculations used for financial reporting, tax filings, and fundraising negotiations well before any actual sale takes place.
Common Mistakes That Distort a Waterfall
A few recurring errors show up again and again in real-world waterfall models. Overlooking a specific class's participation rights, or misreading whether a preference is truly participating or capped, can meaningfully skew results. Missing anti-dilution adjustments. Protections that increase an investor's effective conversion ratio if a later round prices below their original investment. This is another common gap. And failing to account for accrued but unpaid dividends on certain preference classes can understate what senior investors are actually entitled to at exit.
A waterfall analysis is what turns a company's total exit value into an accurate picture of what each investor and shareholder actually receives, and it's essential to valuing private companies with layered capital structures correctly. Liquidation preference, participation rights, seniority, and anti-dilution protections all interact in ways that can shift outcomes dramatically depending on the size of the eventual exit. For anyone valuing a private company, negotiating a term sheet, or pricing a convertible instrument, understanding the waterfall isn't optional. It's the mechanism that determines who actually gets paid, and how much.


